Does EPOS cost price include VAT?
· Jasmine Apps · 15 min read
One of the most confusing parts of setting up products in an EPOS system is understanding what should go into the Cost price field.
Should you enter what you physically paid the supplier? Should you enter the supplier’s price before VAT? If alcohol has 20% VAT, should you add another 20% to its cost price?
And what about food? Many UK venues buy food with little or no VAT, then charge 20% when it is eaten in. The purchase and the sale do not use the same rate.
The answer becomes much easier once you understand that an EPOS system normally calculates gross profit by comparing net sales revenue with net product cost. Purchase VAT and sale VAT are two different things. They do not have to match.
This sits alongside UK VAT on till products, which covers 20%, 5%, and 0% on the selling price.
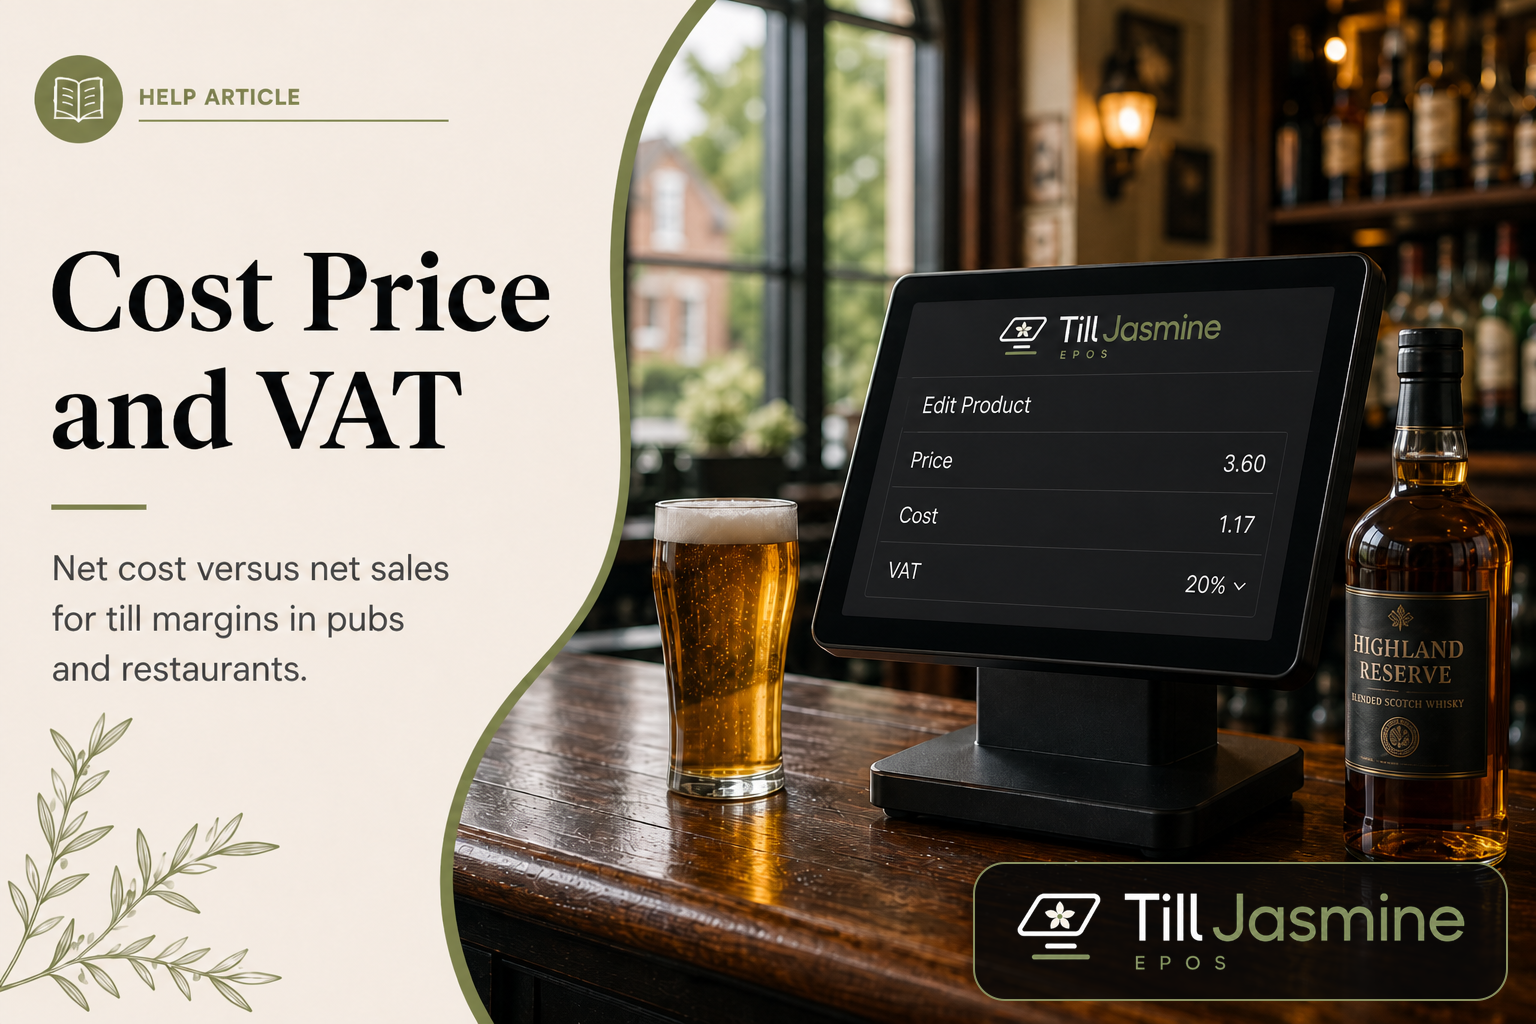
Enter the net cost after any recoverable purchase VAT. Sale VAT is set separately — food and drink do not have to match.
The short answer: enter the cost after recoverable VAT — only if VAT was actually charged
For a VAT-registered business, the cost price entered into an EPOS system will normally be the net cost excluding any VAT that the business can reclaim.
If the supplier did not charge VAT — common on zero-rated food — there is nothing to reclaim. The amount you paid is the cost.
For example, imagine a bottle of alcohol costs £1.17 + VAT. At 20% VAT:
- £1.17 × 20% = £0.234 VAT
- Total invoice amount: £1.404
Your business may physically pay £1.404 to the supplier. Assuming the £0.234 is recoverable input VAT, your underlying product cost for gross-profit purposes remains £1.17.
That is why Till Jasmine expects you to enter £1.17, rather than £1.404. The VAT is dealt with separately through the VAT accounting process.
Food and drink do not use the same VAT on the way in and the way out
In a UK pub, restaurant, or hotel, what you paid the supplier and what you charge the customer are not the same VAT question.
You often pay VAT on some stock and not on other stock. You then set a till VAT rate for how each item is sold — 20%, 5%, or 0%. Those two rates do not have to match, and the cost field does not try to force them to.
| Typical item | Bought from the supplier | Sold on the till | What goes in Cost price |
|---|---|---|---|
| Draught beer, wine, spirits | Usually 20% VAT on the invoice | Usually 20% on the sale | Net goods, after reclaimable VAT |
| Eat-in meal or sandwich | Many food ingredients are zero-rated — no VAT on the purchase | Usually 20% catering | What you paid. Do not invent 20% to strip off |
| Cold takeaway food | Often no VAT on the purchase | Often 0% | What you paid |
| Crisps, sweets, most soft drinks | Usually 20% on the invoice | Usually 20% on the sale | Net goods, after reclaimable VAT |
Till Jasmine compares:
- Net cost — the stock cost after any VAT you can actually reclaim on that purchase
- Net sale — the selling price after the VAT rate set on that till product
Example: food bought without VAT, sold eat-in with VAT
Suppose a sandwich costs £1.20 from a wholesaler and the invoice shows no VAT — the food is zero-rated. You enter Cost price £1.20.
You sell it eaten in for £4.80 including 20% VAT. Net sale is £4.80 ÷ 1.20 = £4.00. Gross profit is £4.00 − £1.20 = £2.80, a 70% margin.
You still account for £0.80 output VAT on the sale. There was no input VAT on the purchase to reclaim. That is normal, not a broken cost.
If you wrongly divided the £1.20 food cost by 1.20 because “we charge VAT”, the till would show a cost of £1.00 and an inflated margin. The business did not get that 20% back from HMRC — it was never charged.
VAT on the selling price is different from VAT on the cost
When you buy stock, any qualifying VAT charged by your supplier is generally called input VAT. When you sell products to your customers, the VAT you account for is generally called output VAT. These should not normally be mixed together when calculating gross profit.
Consider an alcohol product sold through an EPOS for £3.60 including 20% VAT. You cannot simply take 20% of £3.60 to find the VAT, because the £3.60 already includes the VAT:
- £3.60 ÷ 1.20 = £3.00
- Net sale = £3.00
- VAT = £0.60
- Gross customer price = £3.60
Another useful shortcut is: VAT contained in a 20% VAT-inclusive price = Gross Price × 20/120. So £3.60 × 20/120 = £0.60 VAT.
VAT is not 20% of the VAT-inclusive selling price
If a product is sold for £3.60 including VAT, the VAT is not £3.60 × 20% = £0.72.
That would only be correct if £3.60 were the net price before VAT. If £3.60 is already VAT-inclusive, then net price is £3.00, VAT is £0.60, and the VAT portion is one-sixth of a 20% VAT-inclusive selling price.
How Till Jasmine calculates gross profit
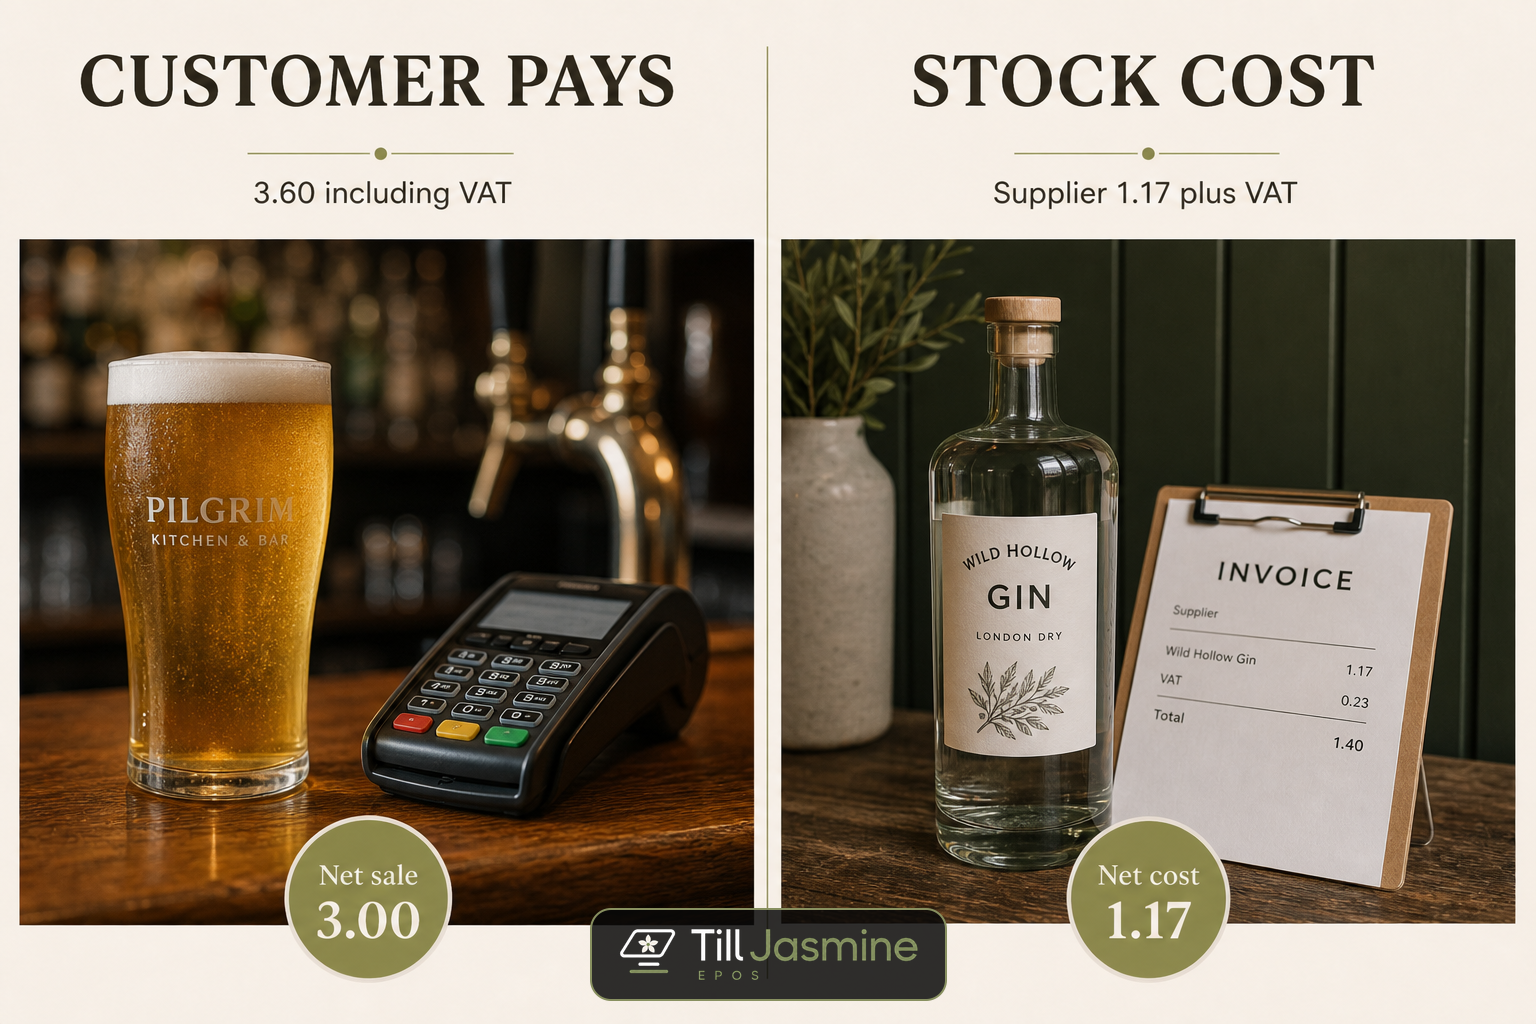
Like with like: net sale versus net cost. The VAT itself is not treated as profit.
Assume selling price including VAT is £3.60, VAT rate is 20%, net selling price is £3.00, and net product cost is £1.17.
Gross profit = net sales − net cost: £3.00 − £1.17 = £1.83.
Gross profit percentage = gross profit ÷ net sales × 100: £1.83 ÷ £3.00 × 100 = 61%.
You collected £3.60 from the customer, but £3.60 is not all sales revenue available to the business. £0.60 represents output VAT, leaving £3.00 of net sales against which the stock cost can be compared.
Why not just use £3.60 minus £1.17?
Because that would incorrectly treat VAT collected from the customer as income. Doing that would produce £3.60 − £1.17 = £2.43, then £2.43 ÷ £3.60 = 67.5%.
That may look like your margin, but for a VAT-registered business it would not be a proper like-for-like gross-profit calculation. The correct comparison is normally net revenue versus net cost: £3.00 − £1.17 = £1.83, giving 61%.
What happens when you buy alcohol?
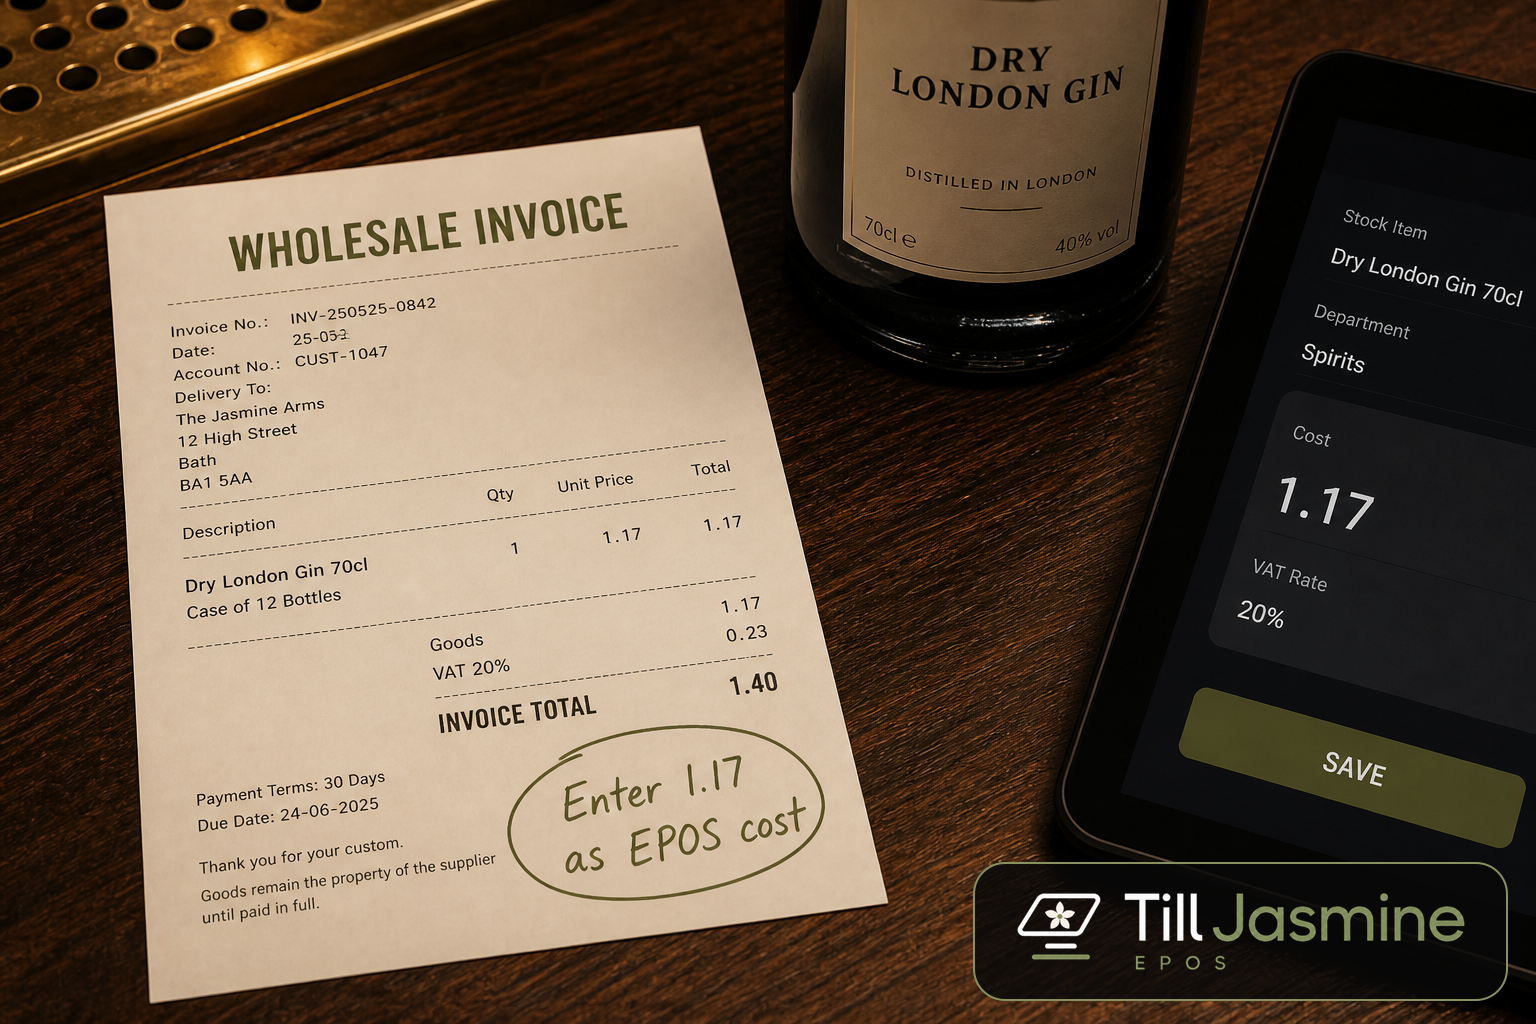
The invoice total is what you pay. The net goods figure is what usually goes in Cost price.
UK alcoholic drinks are subject to the standard rate of VAT, in addition to the separate Alcohol Duty regime. Saying that “alcohol has VAT” does not mean that you should automatically add 20% VAT to the cost entered into your EPOS.
Example 1: supplier charges £1.17 plus VAT
Product cost £1.17, VAT at 20% £0.234, invoice total £1.404. You physically pay approximately £1.40.
If your business is VAT registered and that input VAT is fully recoverable, your net stock cost remains £1.17. That is what belongs in Cost price — not £1.404.
Example 2: supplier says £1.17 including VAT
Remove the VAT: £1.17 ÷ 1.20 = £0.975. If that VAT is reclaimable, the cost you would normally use for margin purposes is approximately £0.98, not £1.17.
The difference can change your gross profit significantly
Using a £3.60 selling price, net selling revenue is £3.00. Suppose £1.17 was actually a VAT-inclusive supplier price. Its net cost would be £1.17 ÷ 1.20 = £0.975.
Gross profit would therefore be £3.00 − £0.975 = £2.025, and the margin 67.5%.
But if you incorrectly entered £1.17 as the net cost, the EPOS would calculate £3.00 − £1.17 = £1.83, a 61% margin. The product would appear less profitable than it really is.
What if my alcohol supplier doesn't show VAT?
Alcohol being a VATable product does not automatically mean every person selling alcohol will show VAT separately. The first question should be: is the supplier VAT registered, and is this a proper VAT invoice?
If your supplier is not VAT registered, they do not simply add 20% VAT to their selling price for you to reclaim. If you genuinely purchase something for £1.17 and no VAT has been charged, then recoverable VAT is £0 and the effective product cost is £1.17. You should not artificially calculate £1.17 + 20% and enter £1.404.
But I still have to charge VAT when I sell it, don't I?
If your business is VAT registered and the sale is standard-rated, yes. Your supplier’s VAT status does not automatically determine the VAT treatment of your sale.
You can buy zero-rated food for £1.20 with no VAT on the invoice, then sell it eaten in for £4.80 including 20% VAT. Cost stays £1.20. Net sale is £4.00. Output VAT is £0.80. The same sandwich taken away cold may be 0% on the till — still with a £1.20 cost.
The same idea applies to drink. Buy a bottle for £1.17 from a supplier who has not charged you VAT. Your effective cost is £1.17. Sell the bottle for £3.60 including 20% VAT. Net sale is £3.00, output VAT is £0.60, and gross profit is £1.83 (61%). There was no input VAT to recover, but there is still output VAT on the sale.
Why don't most tills have “VAT cost” and “non-VAT cost” buttons?
Many EPOS systems store the effective net product cost, then apply the appropriate VAT treatment to the sale separately. The till needs the product cost for stock valuation and gross profit. Purchasing and accounting track the supplier invoice total, input VAT, and VAT liability.
So rather than storing cost £1.17, purchase VAT £0.23, and gross supplier cost £1.40, Till Jasmine simply asks for Cost price: £1.17.
“VATable product” does not mean “add VAT to the EPOS cost”
A product being VATable tells you how VAT applies to the supply. It does not automatically tell you which number belongs in Cost price. Ask: what is my actual cost after recoverable VAT has been removed?
What about Alcohol Duty?
Alcohol Duty is a completely separate tax from VAT. Recoverable VAT is normally removed from your cost calculation. Alcohol Duty generally isn’t.
If the invoice says goods £100, VAT £20, total £120, the £100 net goods figure may already reflect manufacturing costs, import costs, Alcohol Duty, transport, and wholesaler margin. Your EPOS normally cares that your net purchase cost is £100. The recoverable £20 VAT is separate.
A practical bar or restaurant example
Suppose a bar purchases a case of 12 bottles. Supplier invoice: net case cost £14.04, VAT £2.808, invoice total £16.848.
Net cost per bottle: £14.04 ÷ 12 = £1.17. The business therefore enters Cost price £1.17.
The bottle sells for £3.60 including VAT. At 20% VAT, £3.60 ÷ 1.20 = £3.00 net revenue. Gross profit per bottle is £3.00 − £1.17 = £1.83. Gross margin is 61%.
What if you are not VAT registered?
If a business is not VAT registered, it generally cannot recover input VAT. Suppose your supplier charges net stock price £1.17, VAT £0.234, total paid £1.404. For a business unable to recover that VAT, approximately £1.40 is genuinely part of what that stock has cost. Entering only £1.17 could overstate gross profit.
EPOS configuration should match the accounting position of the business using it.
What if some VAT cannot be reclaimed?
The better rule is: use the cost to the business after accounting for any VAT that is actually recoverable. Where input VAT cannot be recovered, some or all of that tax can effectively form part of the business’s cost. Businesses with partial exemption or other special circumstances should confirm their treatment with their accountant.
Why gross profit should usually be calculated excluding VAT
VAT collected on behalf of HMRC does not ordinarily represent trading revenue. Recoverable VAT paid to suppliers does not ordinarily represent a permanent trading expense. Comparing VAT-inclusive revenue against VAT-exclusive cost creates distorted margin percentages.
For ordinary VAT-registered trading: net selling price − net product cost = gross profit.
Worked example: £3.60 selling price and £1.17 cost
| Calculation | Amount |
|---|---|
| Customer selling price | £3.60 |
| VAT rate | 20% |
| Net selling price | £3.00 |
| Output VAT | £0.60 |
| Net product cost | £1.17 |
| Gross profit | £1.83 |
| Gross profit margin | 61% |
The EPOS has not calculated VAT from the £1.17 cost. The VAT on the sale is calculated from the selling price.
Same idea when the purchase had no VAT — eat-in food
| Calculation | Amount |
|---|---|
| Supplier food cost (no VAT charged) | £1.20 |
| EPOS cost price | £1.20 |
| Eat-in selling price | £4.80 |
| Till VAT rate | 20% |
| Net selling price | £4.00 |
| Output VAT | £0.80 |
| Input VAT to reclaim | £0.00 |
| Gross profit | £2.80 |
| Gross profit margin | 70% |
The till charged 20% because the sandwich was eaten in. The cost stayed £1.20 because the supplier never charged VAT.
Common EPOS mistakes
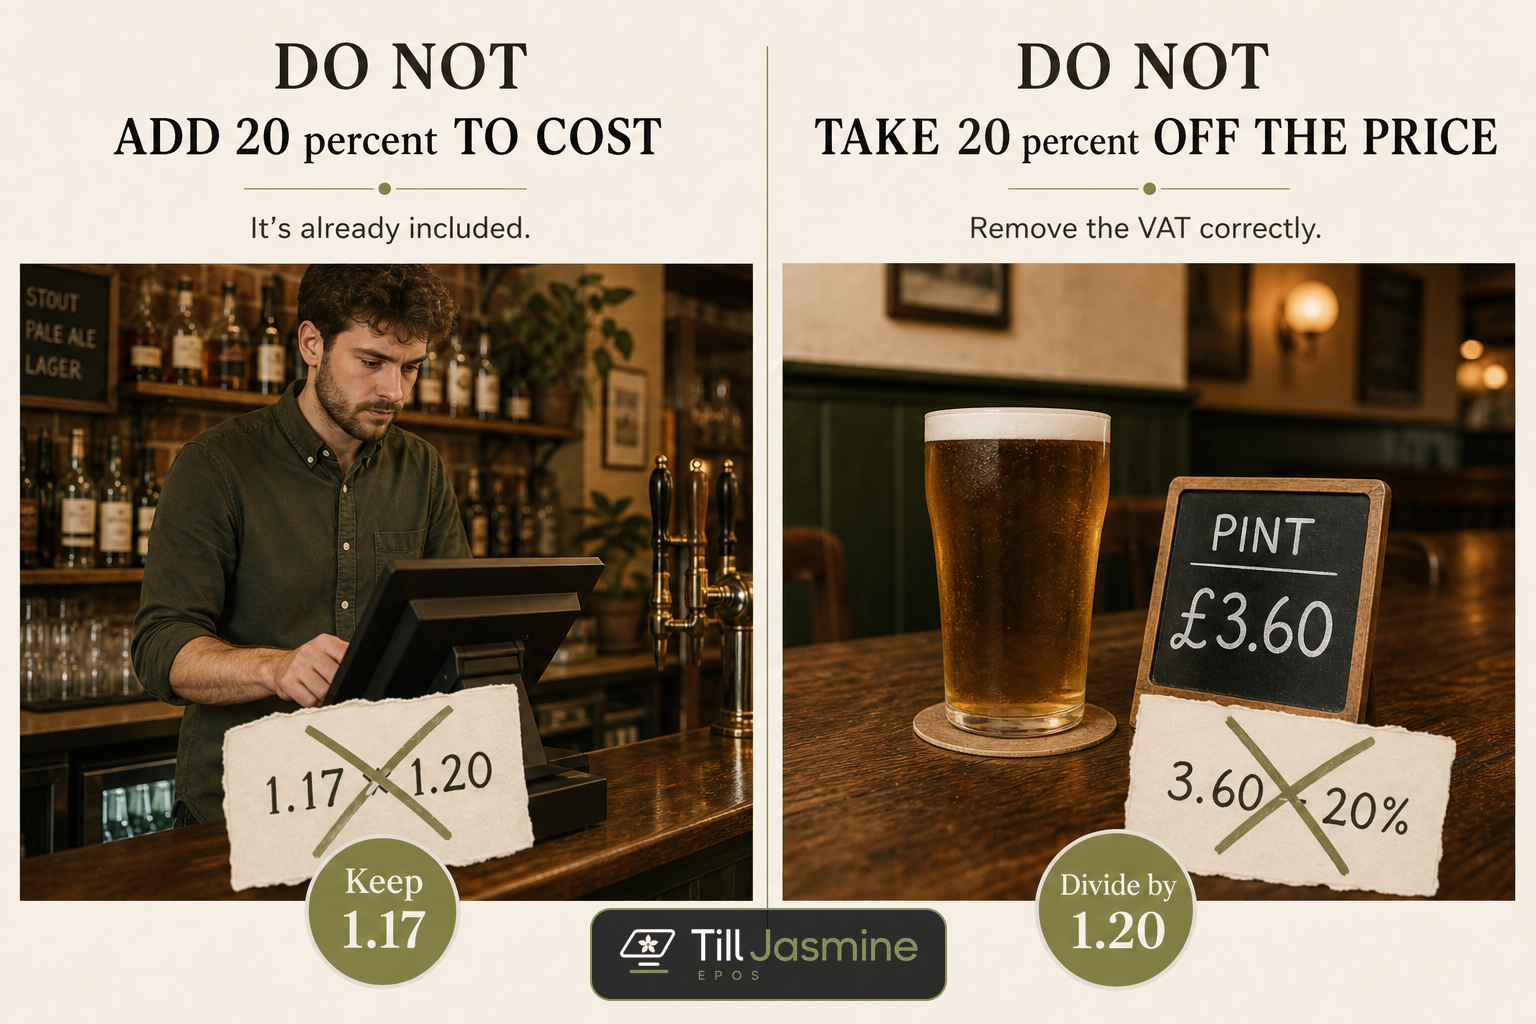
Do not add 20% onto a net cost, and do not take 20% off a VAT-inclusive price. Divide by 1.20 instead.
Adding 20% VAT onto the cost manually
Suppose your supplier invoice says £1.17 + VAT. Some users enter £1.17 × 1.20 = £1.404 as the EPOS cost. If the VAT is recoverable, this makes the margin artificially low: about 53.2% instead of 61%.
Removing 20% from a VAT-inclusive price
Suppose your selling price is £3.60 including VAT. £3.60 − 20% = £2.88 is incorrect, because £3.60 represents 120% of the net price. The correct calculation is £3.60 ÷ 1.20 = £3.00. The same applies to a VAT-inclusive supplier cost: £1.20 including 20% VAT is £1.00 net, not £0.96.
Stripping 20% off a food cost because the till charges 20%
If the supplier did not charge VAT, dividing the food cost by 1.20 is the opposite mistake. The sale rate does not change what the stock cost.
Why accurate cost prices matter so much in hospitality
A few pence entered incorrectly might not look important on one product. Across thousands of sales, inaccurate cost prices distort product margins, category margins, and theoretical gross profit. That affects pricing, menu engineering, supplier negotiations, promotions, and forecasting.
Frequently asked questions
Does alcohol have VAT in the UK?
Yes. Alcoholic products are generally subject to the UK standard VAT rate of 20%. Alcohol Duty is a separate tax.
Should an EPOS cost price include VAT?
For a VAT-registered business that can fully recover the input VAT on the purchase, an EPOS cost price is commonly entered excluding recoverable VAT. Always check how your particular EPOS defines its cost field.
If a bottle costs £1.17 plus VAT, what cost should I enter?
If £1.17 is the supplier's net price and the VAT is fully recoverable, £1.17 is normally the relevant net cost for gross-profit calculations.
If £1.17 already includes 20% VAT, what is the net cost?
Divide it by 1.20: £1.17 ÷ 1.20 = £0.975, approximately £0.98.
Do I add 20% onto an alcohol cost because alcohol is VATable?
Not automatically. If the supplier price is already stated excluding VAT, and the VAT is recoverable, you normally use that net figure. If the supplier has not charged VAT at all, you should not invent a VAT amount simply because the product is alcohol.
Is VAT calculated from the product cost?
Sales VAT is based on the taxable value of the sale, not your purchase cost. Your cost is relevant to profit, but it does not determine how much output VAT is contained in your selling price.
How much VAT is included in a £3.60 price at 20%?
£3.60 ÷ 1.20 = £3.00 net, so VAT is £0.60. It is not £0.72, because £3.60 already includes VAT.
What if my supplier isn't VAT registered?
A supplier who is not VAT registered cannot issue a VAT invoice charging UK VAT. If you pay £1.17 and no VAT has been charged, there is no input VAT to reclaim. Your £1.17 remains the full purchase cost for margin purposes.
What is the difference between VAT and Alcohol Duty?
VAT is a tax on taxable supplies. Alcohol Duty is a separate excise duty applying to alcoholic products. For normal EPOS costing, you should not deduct Alcohol Duty from the supplier's net product price as though it were recoverable VAT.
Why doesn't food cost include VAT if I charge 20% when I sell it?
Purchase VAT and sale VAT are separate. Many food ingredients are bought zero-rated, so there is no input VAT to strip from cost. If you then sell that food eat-in at 20%, Till Jasmine still removes VAT from the selling price. The cost stays the amount you actually paid the supplier.
Can the VAT on a purchase and the VAT on a sale be different?
Yes. A pint is often bought and sold at 20%. A sandwich can be bought at 0% and sold eat-in at 20%, or taken away cold at 0%. Cost price follows the purchase. The till VAT rate follows how the item is sold.
Final takeaway
Compare like with like. For a typical VAT-registered business: selling price including VAT, remove the VAT that applies to that sale, then subtract the net product cost after any recoverable input VAT that was actually charged.
Those two VAT amounts do not have to match. A pint may be 20% in and 20% out. Eat-in food is often 0% in and 20% out. Cold takeaway food may be 0% on both sides.
Drink example: £3.60 customer price → £3.00 net sale → minus £1.17 net cost → £1.83 gross profit → 61% margin.
Food example: £4.80 eat-in price → £4.00 net sale → minus £1.20 zero-rated cost → £2.80 gross profit → 70% margin.
Do not add 20% to a drink cost just because it is alcohol. Do not take 20% off a food cost just because you will charge VAT when it is eaten in.
Official guidance
- VAT Notice 700 — VAT guide
- VAT Notice 700/21 — record keeping and invoices
- HMRC rates of VAT on different goods and services
- Alcohol Duty
- Till Jasmine: UK VAT on till products
This article is general information about UK VAT and EPOS costing. It is not accounting or tax advice. Confirm unusual cases with an accountant or VAT adviser.